
A Comprehensive Scientific, Technological, Economic and Strategic Thesis — 2026
Abstract
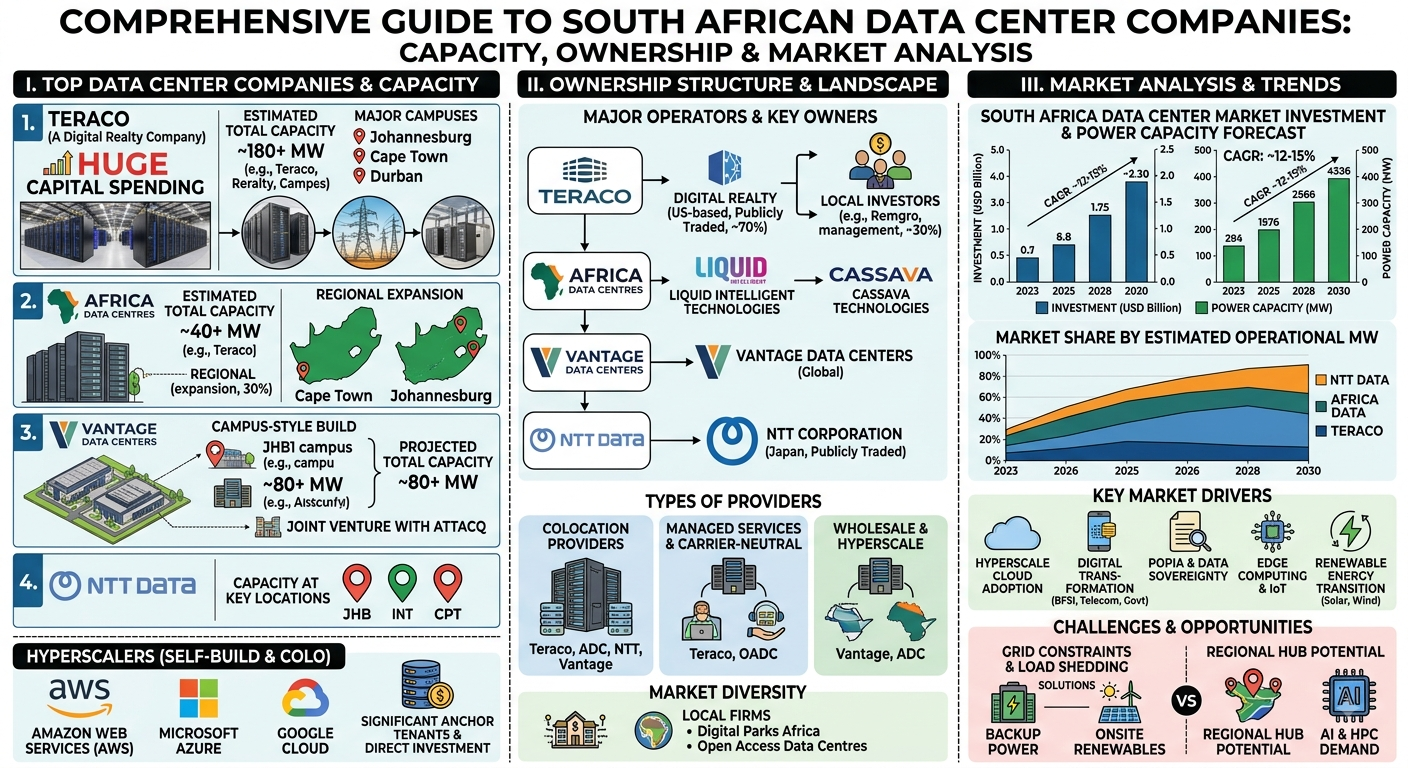
South Africa has become the principal data-centre hub of the African continent. Its position is supported by comparatively advanced telecommunications infrastructure, submarine cable connectivity, financial and commercial activity, cloud adoption, enterprise digitisation, growing artificial-intelligence workloads and the presence of international hyperscale cloud providers.
The country’s data-centre industry is no longer simply a specialised information-technology sector. It has become a strategic component of national infrastructure alongside electricity, telecommunications, transport, financial systems and industrial infrastructure.
This thesis examines the South African data-centre ecosystem through its history, architecture, ownership structures, installed and planned capacity, geographic distribution, operators, hyperscalers, telecommunications networks, energy requirements, cooling systems, fibre connectivity, cloud computing, artificial intelligence, cybersecurity, economics, environmental consequences and future development.
Recent 2026 research places South Africa’s installed data-centre IT capacity at slightly above 500 MW and projects approximately 960 MW by 2030, although published figures differ according to whether they measure IT load, critical power, commissioned capacity or total development pipeline.
1. Introduction
A data centre is a specialised facility designed to house computing systems, storage systems, telecommunications equipment, electrical infrastructure, cooling equipment and security systems.
At its simplest, a data centre can be understood as the physical foundation underneath the digital economy.
Every time a person:
- sends a message;
- watches a video;
- makes a digital payment;
- uses cloud storage;
- searches the internet;
- accesses an online government service;
- uses artificial intelligence;
- conducts an online transaction; or
- operates a business application,
computing infrastructure somewhere processes and stores the associated information.
South Africa therefore occupies an increasingly important position in the African digital ecosystem.
2. The Evolution of South African Data Centres
The industry evolved through several technological generations.
Generation 1 — Corporate computer rooms
Early organisations maintained their own server rooms.
Banks, government departments, universities, telecommunications companies and large corporations operated dedicated computing facilities.
Generation 2 — Internet and telecommunications data centres
The expansion of the internet created demand for professional hosting facilities.
Telecommunications operators began building facilities capable of hosting servers belonging to multiple customers.
Generation 3 — Carrier-neutral colocation
Carrier-neutral facilities changed the market.
Instead of being locked to one telecommunications provider, customers could connect to multiple networks.
Teraco became particularly important in this development and was the first carrier-neutral data-centre provider in sub-Saharan Africa, according to the DBSA study.
Generation 4 — Cloud infrastructure
The arrival of AWS, Microsoft Azure, Google Cloud and other cloud platforms created a new category of demand.
Data centres became foundations for:
- Infrastructure as a Service;
- Platform as a Service;
- Software as a Service;
- artificial intelligence;
- machine learning;
- databases;
- cybersecurity;
- digital financial services; and
- large-scale analytics.
Generation 5 — AI infrastructure
The newest generation is increasingly shaped by AI.
AI systems require enormous quantities of:
- GPU computing;
- high-speed networking;
- electrical power;
- storage;
- cooling;
- specialised semiconductor infrastructure.
This is transforming data-centre design from traditional enterprise computing toward high-density computational infrastructure.
3. South Africa’s Geographic Data-Centre Architecture
South Africa’s data-centre industry is concentrated primarily in Gauteng and the Western Cape.
3.1 Gauteng
Johannesburg and its surrounding industrial areas constitute the country’s largest data-centre cluster.
The advantages include:
- financial-sector concentration;
- major corporate headquarters;
- extensive fibre networks;
- proximity to customers;
- international connectivity;
- established industrial infrastructure;
- availability of large development sites.
Recent industry research indicates that Johannesburg accounts for approximately 72% of South Africa’s operational data-centre capacity under one market definition.
Major locations include:
- Isando;
- Bredell;
- Midrand;
- Samrand;
- Waterfall;
- Randburg;
- Johannesburg CBD and surrounding areas.
3.2 Cape Town
Cape Town is the country’s second major data-centre hub.
Its advantages include:
- submarine cable connectivity;
- geographic separation from Johannesburg;
- proximity to international cable routes;
- renewable-energy opportunities;
- cloud infrastructure;
- growing technology-sector demand.
Cape Town’s importance is increasing particularly for hyperscale, cloud and international connectivity strategies.
3.3 Durban
Durban provides an important coastal and telecommunications location.
Its strategic advantages include:
- port infrastructure;
- submarine cable connectivity;
- proximity to KwaZulu-Natal’s commercial economy;
- geographic redundancy.
3.4 Emerging locations
Other regions are being considered for future development, including:
- Pretoria;
- Eastern Cape;
- Coega;
- Richards Bay;
- Stellenbosch;
- other industrial and special economic zones.
The movement toward secondary locations is strategically important because excessive concentration in one metropolitan region creates infrastructure and resilience risks.
4. Major South African Data-Centre Companies
The South African market contains a mixture of:
- independent colocation operators;
- telecommunications companies;
- cloud infrastructure providers;
- hyperscale operators;
- enterprise data-centre companies;
- government infrastructure providers.
Important participants include:
- Teraco;
- Africa Data Centres;
- Vantage Data Centres;
- Equinix;
- Digital Parks Africa;
- NTT Data;
- BCX;
- MTN Business;
- Vodacom Business;
- Open Access Data Centres;
- SITA.
The DBSA identifies these companies as significant participants in the South African market.
5. Teraco and Digital Realty
Teraco is one of the most important data-centre infrastructure companies in Africa.
Its significance comes from the combination of:
- carrier neutrality;
- interconnection;
- colocation;
- cloud connectivity;
- internet exchange infrastructure;
- large-scale campuses.
Teraco was acquired by Digital Realty, creating a major connection between South Africa’s leading carrier-neutral infrastructure platform and one of the world’s largest data-centre operators.
Major campuses
Important Teraco facilities include:
- Isando;
- Bredell;
- Brackenfell/Cape Town;
- other interconnected facilities.
Recent research identifies the Isando campus at approximately 70 MW of IT load, Bredell at approximately 63 MW and Brackenfell at approximately 50 MW. These figures should be treated as facility-level estimates because capacity definitions vary between sources.
Teraco’s infrastructure is especially important because it connects enterprises, telecommunications networks, cloud providers and internet infrastructure.
6. Africa Data Centres
Africa Data Centres is a major pan-African operator and part of Cassava Technologies.
Its South African footprint includes major facilities around:
- Johannesburg;
- Midrand;
- Samrand;
- Cape Town.
The company is particularly significant because it provides infrastructure for cloud computing, enterprise applications and digital services across Africa.
Its position also connects South Africa’s data-centre economy with the wider African digital infrastructure market.
7. Vantage Data Centres
Vantage has established a major hyperscale-oriented presence in South Africa.
Its Johannesburg campus is located in Waterfall City.
A South African government presentation identifies the Waterfall campus as an approximately 80 MW development, illustrating the scale of the new generation of hyperscale facilities.
Vantage represents a fundamental change in the industry.
Traditional enterprise facilities might be designed around thousands of servers.
Hyperscale campuses can be designed around extremely large deployments and are increasingly suitable for cloud and AI infrastructure.
8. Equinix
Equinix is one of the world’s major global interconnection and data-centre companies.
Its Johannesburg presence provides another international interconnection platform within South Africa.
The company is also planning major expansion in Cape Town.
In July 2026, South African authorities approved Equinix’s proposal for two Cape Town data centres requiring approximately 170 MW of power capacity. Reuters described the project as one of the country’s largest proposed data-centre developments.
This illustrates the scale of future demand.
9. Digital Parks Africa
Digital Parks Africa is another important South African operator.
Its Samrand facility is identified in recent market research at approximately 24 MW of IT load.
Its location demonstrates the strategic importance of Gauteng’s industrial corridors for large digital infrastructure.
10. NTT Data
NTT Data provides enterprise-oriented technology infrastructure and operates data-centre facilities in South Africa.
Its Johannesburg facility is identified in recent market research at approximately 12 MW of IT load.
NTT’s global network gives South African enterprises access to an international technology ecosystem.
11. BCX
BCX is a major South African ICT company owned by Telkom.
Its services extend beyond physical data centres into:
- cloud;
- networking;
- cybersecurity;
- managed services;
- enterprise ICT;
- digital transformation.
This makes BCX an example of an integrated telecommunications and IT infrastructure company rather than a pure-play colocation operator.
12. MTN Business and Vodacom Business
South Africa’s telecommunications companies also participate in data-centre infrastructure.
MTN Business
MTN Business provides enterprise connectivity, cloud, managed services and data-centre capabilities.
Vodacom Business
Vodacom Business similarly combines:
- telecommunications;
- cloud;
- enterprise IT;
- connectivity;
- hosting;
- managed infrastructure.
The convergence of telecommunications and data-centre infrastructure is strategically important because modern digital services require both computing and network connectivity.
13. Open Access Data Centres
Open Access Data Centres is part of the WIOCC ecosystem.
Its strategy demonstrates another important development:
African digital infrastructure is increasingly being built as interconnected ecosystems rather than isolated facilities.
The value proposition involves combining:
- data centres;
- fibre;
- subsea cables;
- internet connectivity;
- cloud connectivity.
14. Government Data Centres
The private sector does not control all South African computing infrastructure.
Government infrastructure includes facilities associated with the State Information Technology Agency.
SITA operates major government data-centre infrastructure in Pretoria and network infrastructure across several provinces.
Government data centres support:
- public administration;
- government databases;
- citizen services;
- taxation;
- justice systems;
- social services;
- national information systems.
15. Hyperscalers
South Africa is also home to major international cloud platforms.
Important hyperscale/cloud participants include:
Amazon Web Services
AWS operates cloud infrastructure in Cape Town.
Microsoft Azure
Microsoft operates the South Africa North and South Africa West cloud regions.
Google Cloud
Google operates its South African cloud region.
Huawei Cloud
Huawei has also invested heavily in the African cloud ecosystem.
These companies are fundamentally different from traditional colocation providers.
A colocation company provides physical infrastructure.
A hyperscaler provides computational services on top of that infrastructure.
16. The Data-Centre Value Chain
The industry can be represented as:
Electricity
↓
Grid / Renewable Generation
↓
Substation
↓
Data Centre
↓
Servers
↓
CPU / GPU / Accelerators
↓
Storage
↓
Network
↓
Fibre
↓
Internet Exchange / Subsea Cable
↓
Cloud / AI / Applications
↓
Businesses and Consumers
This makes the data centre a central node connecting energy infrastructure to the digital economy.
17. Electricity: The Most Important Constraint
A modern data centre cannot operate without extremely reliable electricity.
The electrical system generally contains:
- utility connection;
- substations;
- transformers;
- switchgear;
- UPS systems;
- batteries;
- generators;
- automatic transfer systems;
- power distribution units;
- rack-level power systems.
The industry therefore has a close relationship with Eskom and municipal electricity networks.
The improvement in South Africa’s electricity availability in 2026 has increased interest in using the country’s power infrastructure to attract new data-centre investment. Recent reporting says Eskom is actively seeking data-centre customers as part of its strategy to utilise available generation capacity.
18. Renewable Energy
The future data centre will increasingly be connected to renewable electricity.
Potential sources include:
- solar photovoltaic;
- wind;
- battery storage;
- wheeling arrangements;
- power-purchase agreements;
- hybrid generation.
This is important because hyperscalers and multinational companies increasingly have environmental and carbon-reduction commitments.
The future model may therefore become:
Data Centre + Solar + Wind + Battery + Grid
rather than:
Data Centre + Grid only
19. Cooling Technology
Servers convert electrical energy into heat.
That heat must be removed continuously.
Traditional cooling systems use:
- computer-room air conditioning;
- chilled water;
- cooling towers;
- air handlers.
AI introduces new challenges.
High-density GPU systems can produce dramatically greater heat loads per rack than traditional enterprise servers.
Consequently, the industry is increasingly examining:
- direct-to-chip liquid cooling;
- rear-door heat exchangers;
- immersion cooling;
- advanced heat recovery;
- high-efficiency cooling systems.
20. Water
Water is an important environmental issue.
Some cooling technologies consume significant quantities of water.
This creates a fundamental engineering trade-off:
less electricity consumption may sometimes require more water, while reducing water consumption may increase electrical demand.
The optimal solution depends on:
- climate;
- electricity source;
- water availability;
- facility design;
- local environmental conditions.
Cape Town’s water situation makes this issue particularly important.
21. Fibre-Optic Infrastructure
Data centres are valuable only when they are connected.
South Africa possesses extensive fibre infrastructure connecting:
- Johannesburg;
- Pretoria;
- Cape Town;
- Durban;
- regional African markets;
- international submarine cables.
Fibre provides:
- low latency;
- high bandwidth;
- redundancy;
- cloud connectivity;
- internet access.
22. Submarine Cables
South Africa’s position on the southern African coastline gives it access to multiple submarine cable systems.
These cables connect South Africa with:
- Europe;
- Asia;
- the Middle East;
- other African countries;
- international internet exchange points.
Cape Town benefits particularly from its coastal location.
This is one reason Cape Town is increasingly attractive for international digital infrastructure.
23. NAPAfrica
NAPAfrica is an important component of South Africa’s internet infrastructure.
An internet exchange allows networks to exchange traffic directly.
Instead of traffic taking unnecessary international routes, local networks can exchange information locally.
This improves:
- latency;
- resilience;
- bandwidth efficiency;
- network economics.
It also strengthens South Africa’s position as an African internet hub.
24. Data Centres and Artificial Intelligence
AI is potentially the most important future driver of data-centre expansion.
Traditional computing workloads include:
- databases;
- websites;
- email;
- enterprise software;
- video streaming.
AI adds:
- model training;
- inference;
- vector databases;
- large-scale data processing;
- GPU computing;
- high-performance networking.
AI infrastructure therefore changes the engineering requirements of the data centre.
25. GPU Density
A conventional server rack might operate at relatively moderate power densities.
AI racks can require dramatically greater power.
This creates requirements for:
- larger electrical feeds;
- high-capacity cooling;
- liquid cooling;
- advanced networking;
- specialised power distribution;
- stronger physical infrastructure.
The data centre is consequently becoming closer to a specialised power-and-computing plant.
26. Data-Centre Market Growth
Current estimates differ because researchers use different definitions.
One recent South African market study estimates installed IT capacity at slightly above 500 MW in 2025 and approximately 960 MW by 2030. The same study estimates market value rising from roughly US$0.58 billion in 2025 to approximately US$1.25 billion in 2030.
Other sources use different definitions and report substantially different figures.
Therefore:
Capacity figures should always specify whether they refer to IT load, critical power, commissioned capacity, planned capacity or total campus capacity.
This distinction is essential when comparing operators.
27. Ownership Structure
The industry demonstrates several forms of ownership.
International ownership
Examples include:
- Digital Realty;
- Equinix;
- Vantage;
- NTT.
African ownership
Examples include:
- Cassava Technologies/Africa Data Centres;
- WIOCC/Open Access Data Centres.
South African corporate ownership
Examples include:
- Telkom/BCX;
- MTN;
- Vodacom.
Government ownership
SITA represents the public-sector infrastructure category.
This mixture gives South Africa an unusually diverse data-centre ecosystem.
28. Economic Importance
Data centres create economic value through:
- construction;
- engineering;
- telecommunications;
- electrical infrastructure;
- cooling systems;
- cybersecurity;
- cloud computing;
- software;
- professional services;
- real estate;
- renewable energy.
They also attract hyperscalers and international technology investment.
The indirect economic effect can therefore be significantly larger than the number of people physically employed inside a data centre.
29. Data Centres and National Digital Sovereignty
Data sovereignty is becoming increasingly important.
Countries want strategic information to remain subject to appropriate national laws and governance.
South African data centres can support:
- financial data;
- government information;
- health information;
- corporate information;
- African cloud services;
- AI workloads.
Local infrastructure can reduce dependence on distant international facilities.
30. Cybersecurity
A data centre is a major cybersecurity target because it concentrates valuable information and computing resources.
Security must therefore exist at multiple levels:
Physical
- fences;
- access control;
- biometric authentication;
- surveillance;
- security personnel.
Network
- firewalls;
- intrusion detection;
- segmentation;
- encryption.
Computing
- endpoint security;
- identity management;
- secure operating systems.
Data
- encryption;
- backups;
- access controls;
- disaster recovery.
31. Physical Resilience
Tier-style resilience concepts are used throughout the industry.
A resilient facility typically includes redundancy in:
- power;
- cooling;
- network connectivity;
- generators;
- UPS systems;
- storage;
- communications.
The objective is to prevent one component from becoming a single point of failure.
32. Disaster Recovery
South Africa’s geography allows operators to build geographically separated facilities.
For example:
Johannesburg
can be paired with
Cape Town
for disaster recovery and business continuity.
This geographic separation can protect organisations against regional failures.
33. The Importance of Johannesburg
Johannesburg’s dominance is not accidental.
The city combines:
- financial institutions;
- telecommunications;
- fibre;
- corporate headquarters;
- cloud customers;
- industrial land;
- transport infrastructure.
The combination creates a powerful network effect.
More data centres attract more networks.
More networks attract more cloud providers.
More cloud providers attract more businesses.
More businesses generate demand for additional data centres.
This creates a self-reinforcing digital infrastructure ecosystem.
34. The Strategic Importance of Cape Town
Cape Town offers a different strategic model.
Its strengths include:
- submarine cables;
- international connectivity;
- coastal location;
- technology-sector concentration;
- renewable-energy opportunities;
- geographical separation from Gauteng.
Cape Town can therefore become an international gateway as well as a domestic computing hub.
35. Major Challenges
The industry’s largest challenges include:
- electricity availability;
- grid connection capacity;
- water availability;
- land;
- fibre redundancy;
- environmental approval;
- construction costs;
- imported equipment;
- semiconductor availability;
- cybersecurity;
- skilled engineering personnel;
- AI power density.
36. Environmental Sustainability
Data centres should increasingly be evaluated using:
- Power Usage Effectiveness (PUE);
- Water Usage Effectiveness (WUE);
- carbon intensity;
- renewable-energy percentage;
- equipment life-cycle analysis;
- waste management;
- heat recovery.
The goal should not simply be constructing larger facilities.
The goal should be:
more computing per unit of electricity, water and material.
37. Future Data-Centre Architecture
The future South African data centre is likely to combine:
Grid
Renewable Power
Battery Storage
High-Density Computing
Liquid Cooling
AI Accelerators
High-Speed Fibre
Cloud Platforms
Cybersecurity
Automation
Artificial Intelligence
This represents a transition from the traditional server room to a highly automated digital-industrial facility.
38. South Africa’s African Leadership
South Africa’s importance extends beyond its borders.
Its data centres provide infrastructure for the wider African digital economy.
International cloud providers, telecommunications networks and African enterprises can use South African infrastructure as a regional platform.
Recent reporting estimates that South Africa hosts roughly 70% of Africa’s data-centre capacity, although the precise percentage depends on market definitions.
39. Strategic Competition
The South African market is increasingly competitive.
The principal competitive dimensions are:
| Dimension | Strategic Importance |
|---|---|
| Electricity | Extremely high |
| Fibre | Extremely high |
| Cloud connectivity | Extremely high |
| Land | High |
| Water | High |
| Renewable energy | Increasingly high |
| Cybersecurity | Extremely high |
| AI capability | Rapidly increasing |
| Skilled labour | High |
| International connectivity | Extremely high |
The winner will not necessarily be the company with the largest building.
The winner will be the operator that integrates these systems most effectively.
40. South Africa’s Data-Centre Future to 2030
The next phase is likely to be characterised by:
1. Hyperscale expansion
Large campuses will continue to grow.
2. AI infrastructure
GPU-intensive computing will increase.
3. Renewable electricity
More operators will procure renewable energy.
4. Liquid cooling
High-density AI systems will accelerate adoption.
5. Edge computing
Smaller facilities will appear closer to users.
6. Regional African connectivity
South African facilities will serve additional African markets.
7. Greater automation
AI will increasingly control facility optimisation.
41. Strategic Recommendations
South Africa should develop a coordinated national data-centre strategy.
Recommendation 1 — Expand electricity infrastructure
Data-centre growth must be coordinated with generation and transmission capacity.
Recommendation 2 — Encourage renewable energy
Renewable generation should be integrated with large digital infrastructure projects.
Recommendation 3 — Protect water resources
Data-centre development should account for local water scarcity.
Recommendation 4 — Expand fibre
More geographically diverse fibre routes should be developed.
Recommendation 5 — Develop technical skills
South Africa needs more:
- electrical engineers;
- mechanical engineers;
- network engineers;
- cybersecurity specialists;
- cloud engineers;
- AI engineers;
- data-centre technicians.
Recommendation 6 — Develop secondary hubs
Investment should extend beyond Johannesburg and Cape Town.
Recommendation 7 — Support African cloud infrastructure
South Africa can become a computing and connectivity gateway for the wider continent.
42. Conclusion
South Africa’s data-centre industry has evolved from a relatively specialised IT function into strategic national infrastructure.
Companies such as Teraco/Digital Realty, Africa Data Centres, Vantage, Equinix, Digital Parks Africa, NTT Data, BCX, MTN Business, Vodacom Business and Open Access Data Centres form an increasingly sophisticated ecosystem.
The industry’s future will be determined by five fundamental resources:
electricity + connectivity + land + cooling + computing demand.
Among these, electricity is becoming particularly decisive because AI is dramatically increasing computational density.
The next generation of South African data centres will therefore not merely be buildings containing servers. They will be integrated technological infrastructures combining electrical engineering, mechanical engineering, telecommunications, semiconductor computing, cloud platforms, artificial intelligence, cybersecurity, renewable energy and advanced cooling.
South Africa’s competitive advantage is its existing telecommunications infrastructure, financial economy, international connectivity and established data-centre ecosystem.
Its principal risks are electricity infrastructure, water availability, environmental pressures, skills shortages and the rapidly increasing power requirements of AI.
If these challenges are managed effectively, South Africa can strengthen its position as the principal digital infrastructure hub of Africa and potentially become one of the world’s important emerging locations for cloud, interconnection and AI infrastructure.
Selected 2026 Research Base
The analysis should be updated continuously because data-centre capacity, ownership and construction pipelines change rapidly.
Key recent sources include:
- Development Bank of Southern Africa’s South Africa’s Digital Infrastructure Investment Study, which examines the country’s data-centre participants and future infrastructure requirements.
- Wesgro’s 2026 overview of the global and African data-centre landscape, including South African facility-level capacity estimates and market projections.
- South African government material describing the geographic distribution of data centres and major operators.
- Reuters reporting from July 2026 concerning Equinix’s planned Cape Town expansion.
- Recent Financial Times reporting on Eskom’s strategy to attract data-centre electricity demand.
Important methodological note: Published data-centre capacity numbers should not be combined mechanically. A 20 MW IT-load figure, a 20 MW critical-power figure and a 20 MW campus-development figure can describe materially different things. A rigorous market study should therefore maintain separate columns for operational IT load, critical power, commissioned capacity, under-construction capacity, permitted capacity and announced/pipeline capacity.

Be First to Comment