
A Comprehensive Thesis on the Geography, Infrastructure, Economics, Energy, Technology, and Future of Global Data Centers
Abstract
Data centers have become one of the most important forms of infrastructure in the modern digital economy. Behind cloud computing, artificial intelligence, online banking, telecommunications, streaming, e-commerce, government services, scientific research, social media, enterprise software, and countless other digital activities lies a physical infrastructure of buildings, servers, storage systems, networking equipment, electrical grids, cooling systems, security systems, and telecommunications connections.
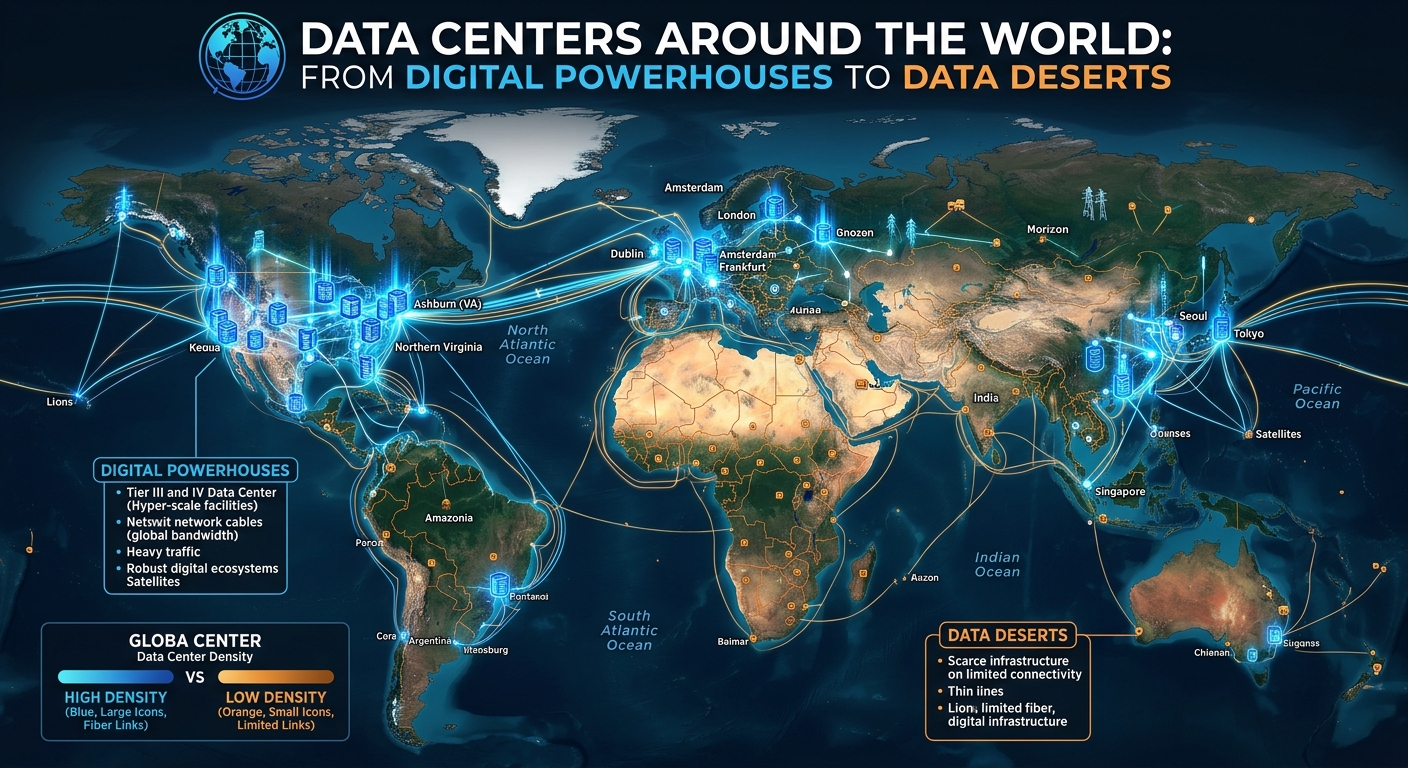
The global geography of data centers, however, is highly unequal. Some regions have developed enormous concentrations of computing capacity and have become digital powerhouses, while other regions remain data deserts, possessing comparatively little local computing infrastructure despite large populations and rapidly increasing digital demand. This geographical imbalance has implications for economic development, technological sovereignty, cybersecurity, latency, employment, energy consumption, investment, and access to artificial intelligence.
Recent estimates illustrate the scale of this concentration. Global installed data-center capacity reached roughly 122.2 GW in 2024/early 2025 in one widely cited dataset, with the United States and China accounting for a very large share. The ITU has also identified substantial future data-center capacity gaps in Africa, South Asia, Latin America, the Arab States and parts of Asia-Pacific.
At the same time, the traditional geography of data centers is beginning to change. Artificial intelligence requires exceptionally large quantities of computing power and electricity, encouraging developers to move toward locations where land, electricity, cooling resources, and grid connections are available. In 2026, European developers were increasingly looking beyond traditional metropolitan hubs because power availability had become a major determinant of location.
This thesis examines the global data-center ecosystem, explains why data centers cluster in particular countries and cities, investigates the causes of data deserts, evaluates their economic and social consequences, and proposes a framework for building a more geographically balanced digital infrastructure.
1. Introduction
The phrase “the cloud” can create the impression that digital information exists somewhere intangible. In reality, cloud computing depends on physical infrastructure.
Every email, video call, online transaction, artificial-intelligence query, digital photograph, database record, streaming service, website and software application ultimately requires computing resources somewhere.
These resources are concentrated inside data centers.
A modern data center can range from a small enterprise facility containing a few server racks to enormous hyperscale campuses containing tens or even hundreds of megawatts of IT capacity.
The world’s digital economy therefore has a physical geography.
Some locations contain enormous concentrations of computing infrastructure. Northern Virginia, for example, has become one of the world’s largest data-center markets, while major European hubs include London, Frankfurt, Paris and Amsterdam. Asia-Pacific has major centers such as Tokyo and Singapore, alongside rapidly expanding secondary markets.
Other parts of the world have comparatively little capacity.
This creates an important technological divide:
Where data is produced and consumed is not necessarily where data is processed and stored.
That distinction is central to understanding the global digital economy.
2. What Is a Data Center?
A data center is a specialized facility designed to house and operate information-technology infrastructure.
Its major components include:
- Computing servers
- Storage systems
- Network equipment
- Power distribution
- Backup power
- Cooling infrastructure
- Fire detection and suppression
- Physical security
- Monitoring systems
- Telecommunications connectivity
- Building-management systems
- Cybersecurity infrastructure
- Operations personnel
- Automation and artificial intelligence
A simplified architecture is:
Electricity → Power infrastructure → Servers → Storage → Network → Applications → Users
But the real system is more complex.
A data center must simultaneously manage:
Power + computation + cooling + connectivity + security + reliability + maintenance.
Failure in any one of these systems can affect the availability of digital services.
3. The Evolution of Data Centers
The history of data centers can broadly be divided into several periods.
3.1 Mainframe Era
During the early computer era, organizations operated large centralized machines.
Government agencies, universities, banks and large corporations maintained specialized computer rooms.
These facilities established the basic principle of centralized computing.
3.2 Enterprise Data Centers
As businesses adopted computers, organizations built dedicated facilities containing servers, storage and networking equipment.
Banks, telecommunications companies, governments and universities became major data-center operators.
3.3 Internet Data Centers
The growth of the Internet created demand for facilities capable of connecting servers to global telecommunications networks.
Data centers increasingly became commercial infrastructure rather than merely internal corporate facilities.
3.4 Colocation
Colocation companies began providing space, electricity, cooling and connectivity to organizations that did not want to construct their own facilities.
This helped create a professional data-center industry.
3.5 Cloud Computing
Cloud providers transformed the industry.
Instead of organizations purchasing and maintaining all their own servers, they could rent computing, storage and software resources.
This produced enormous hyperscale data-center campuses.
3.6 Artificial Intelligence Era
The latest transformation is being driven by AI.
AI workloads require powerful accelerators, enormous datasets, high-speed networking and large quantities of electricity.
Consequently, the data center is evolving from a conventional server facility into an increasingly sophisticated AI computing factory.
4. The Global Data-Center Landscape
The worldwide data-center industry is highly concentrated.
One 2025 assessment estimated global installed capacity at approximately 122.2 GW, with the United States holding about 53.7 GW and China about 31.9 GW in the cited dataset.
Another visualization based on industry data estimated 122.2 GW globally in 2024 and found that the United States and China together represented approximately 70% of global capacity.
These figures demonstrate an important principle:
Data-center capacity does not correspond simply to population.
A country can have a very large population but relatively little computing infrastructure.
Conversely, a country with a comparatively smaller population can host enormous quantities of global computing capacity.
This occurs because data centers serve international markets.
5. The Digital Powerhouses
5.1 United States
The United States is the world’s most important data-center ecosystem.
Its advantages include:
- enormous cloud-computing demand;
- advanced telecommunications;
- abundant investment capital;
- large technology companies;
- semiconductor and AI ecosystems;
- extensive electricity infrastructure;
- mature enterprise markets;
- highly developed financial systems;
- large numbers of hyperscale facilities.
Northern Virginia has become particularly important.
Other major markets include Atlanta, Phoenix, Chicago, Dallas-Fort Worth and Silicon Valley.
CBRE reported strong expansion in the leading North American markets during 2025, with inventory in its four largest markets increasing substantially year over year.
The United States therefore represents a classic digital powerhouse.
6. China
China represents another major center of global computing infrastructure.
Its advantages include:
- enormous domestic Internet usage;
- major cloud companies;
- large-scale digital services;
- extensive telecommunications infrastructure;
- significant technology investment;
- large industrial supply chains;
- rapidly expanding AI requirements.
China also illustrates an important difference between data-center capacity and global Internet geography.
A significant portion of Chinese computing infrastructure supports China’s enormous domestic digital economy.
7. Europe
Europe represents another major global data-center region.
Important markets include:
- United Kingdom;
- Germany;
- France;
- Netherlands;
- Ireland;
- Spain;
- Nordic countries.
The traditional European core includes London, Frankfurt, Amsterdam and Paris.
However, European expansion is increasingly constrained by:
- electricity availability;
- land prices;
- grid congestion;
- planning regulations;
- environmental requirements;
- water considerations.
CBRE reported that Europe’s leading markets continued to experience strong demand while power constraints limited new supply.
This is causing a geographical transition.
Developers increasingly investigate locations outside traditional metropolitan centers.
Recent reporting indicates that European AI data-center projects are moving farther from major cities because electricity and land availability have become increasingly important.
8. Asia-Pacific
Asia-Pacific is one of the world’s fastest-growing data-center regions.
Important markets include:
- Japan;
- Singapore;
- Australia;
- South Korea;
- India;
- Hong Kong;
- Malaysia;
- Indonesia.
Singapore became a major regional hub because of its connectivity, financial importance and proximity to major Asian markets.
However, limited land and electricity have encouraged development elsewhere.
Malaysia, particularly Johor, has emerged as an important secondary market.
Australia is also expanding its data-center ecosystem.
Japan remains strategically important because of its large economy, technology sector and proximity to Asian markets.
9. India: A Major Emerging Computing Power
India deserves special attention.
It has:
- one of the world’s largest populations;
- rapidly increasing Internet usage;
- major software and technology industries;
- expanding cloud adoption;
- growing AI demand;
- major telecommunications infrastructure;
- increasing digital government services.
Yet India’s digital infrastructure requirements remain enormous.
The ITU estimates a substantial data-center capacity gap in South Asia, with India representing most of that regional requirement.
India therefore demonstrates how a country can simultaneously possess a rapidly expanding technology economy and a significant need for additional computing infrastructure.
10. Latin America
Latin America is another important emerging region.
Brazil is the largest market in many regional measurements.
Other important locations include:
- Chile;
- Mexico;
- Colombia;
- Argentina.
São Paulo has developed into the dominant Latin American data-center market.
Santiago has also expanded rapidly.
CBRE reported significant inventory and demand growth in major Latin American markets during 2025.
However, electricity availability, telecommunications infrastructure, financing and regulatory uncertainty can restrict development.
11. The Middle East
The Middle East is increasingly becoming a major digital infrastructure region.
Countries such as:
- United Arab Emirates;
- Saudi Arabia;
- Qatar;
- Bahrain;
- Oman
are investing in cloud computing, AI and digital government.
The region has several strategic advantages:
- large capital availability;
- ambitious digital transformation programs;
- increasing cloud adoption;
- strategic geographical position;
- growing demand for AI.
Its principal challenges include:
- extreme temperatures;
- cooling requirements;
- water scarcity;
- energy management.
The Middle East therefore presents a fascinating technological paradox:
abundant energy potential but challenging environmental conditions.
12. Africa: The Data-Desert Problem
Africa represents one of the most important examples of the global data-center imbalance.
The continent has a huge population and rapidly increasing digital demand, yet its share of global data-center infrastructure remains comparatively small.
The ITU estimates a 6 GW data-center capacity gap for Africa under its methodology.
Other industry estimates have similarly shown Africa’s installed capacity to be a very small fraction of the global total.
This creates what can reasonably be called a data desert.
A data desert does not mean that people have no Internet.
Rather, it means:
The region consumes and generates substantial amounts of digital information but possesses insufficient local computing infrastructure to process, store and distribute that information efficiently.
13. Why Data Deserts Exist
Several factors contribute to data deserts.
13.1 Electricity
Data centers require reliable electricity 24 hours a day.
A facility cannot tolerate frequent interruptions.
Therefore, countries with unstable grids face difficulties attracting hyperscale investment.
13.2 Telecommunications
A data center needs high-capacity fiber networks.
International submarine cables are particularly important.
A country can possess excellent mobile networks while still having inadequate domestic data-center capacity.
13.3 Capital
Large data centers can require enormous capital investments.
Financing conditions therefore strongly influence development.
13.4 Skills
Data centers require:
- electrical engineers;
- mechanical engineers;
- network engineers;
- cybersecurity specialists;
- software engineers;
- technicians;
- facilities managers;
- AI specialists.
A shortage of technical skills can constrain expansion.
13.5 Regulation
Investment depends upon:
- land regulations;
- energy policies;
- taxation;
- telecommunications regulation;
- environmental rules;
- data protection laws.
Uncertainty can discourage investment.
13.6 Market Demand
Hyperscale companies prioritize locations where sufficient demand exists or where facilities can efficiently serve multiple markets.
14. Data Centers and Electricity
Electricity is becoming one of the defining constraints of the global data-center industry.
The conventional question was:
Where are the customers?
The emerging question is increasingly:
Where can we obtain enough electricity?
AI has accelerated this transition.
Large AI facilities require enormous computing capacity.
Consequently, developers are increasingly examining:
- electricity generation;
- transmission capacity;
- grid connection;
- renewable energy;
- nuclear power;
- natural-gas generation;
- battery storage;
- power-purchase agreements.
CBRE identified power availability as one of the principal constraints on global data-center growth.
15. Data Centers and Cooling
Computers generate heat.
The greater the computing density, the greater the cooling challenge.
Traditional facilities primarily use air cooling.
AI infrastructure increasingly encourages more advanced approaches, including liquid cooling.
Cooling systems may include:
- chillers;
- cooling towers;
- computer-room air-conditioning systems;
- pumps;
- heat exchangers;
- liquid-cooling loops;
- direct-to-chip cooling.
This introduces another geographical factor:
Climate and water availability influence data-center design.
Cold regions can offer natural cooling advantages, although electricity, connectivity and other factors remain equally important.
16. The Physical Anatomy of a Modern Data Center
A large modern data center can be understood as a collection of interconnected layers.
Layer 1: Land
The facility requires suitable land.
Layer 2: Building
The building provides physical protection.
Layer 3: Electrical Infrastructure
Electricity enters through substations and distribution systems.
Layer 4: Backup Power
Generators, batteries and UPS systems maintain continuity.
Layer 5: Cooling
Heat is removed from computing equipment.
Layer 6: Computing
Servers perform calculations.
Layer 7: Storage
Data is stored on high-capacity systems.
Layer 8: Networking
Routers, switches and optical systems connect computers to users.
Layer 9: Software
Virtualization, operating systems, databases and cloud platforms manage workloads.
Layer 10: Security
Physical and cybersecurity protect the infrastructure.
The complete system resembles:
Land → Building → Power → Cooling → Compute → Storage → Network → Software → Digital Services
17. Hyperscale Data Centers
Hyperscale facilities are among the largest forms of computing infrastructure.
They are generally associated with major cloud and technology companies.
Their characteristics include:
- massive computing capacity;
- high-speed networks;
- extensive automation;
- large electricity requirements;
- sophisticated cooling;
- multiple redundant systems;
- enormous storage capacity.
Hyperscale infrastructure has become increasingly important because cloud computing and AI require large-scale computing resources.
Industry research indicates that hyperscale operators have steadily increased their share of global data-center capacity.
18. Edge Data Centers
Not all computing should occur in enormous centralized facilities.
Some applications require extremely low latency.
Examples include:
- telecommunications;
- industrial automation;
- autonomous systems;
- gaming;
- smart cities;
- financial services;
- real-time analytics.
Edge computing places smaller computing facilities closer to users.
The future therefore may not be:
Big data centers OR small data centers.
Instead, it is likely to be:
Hyperscale + Regional + Edge Computing
working together.
19. Data Sovereignty
Data-center geography also creates a political and legal question:
Where should a country’s data physically reside?
Governments increasingly care about:
- privacy;
- national security;
- financial information;
- healthcare information;
- government records;
- critical infrastructure;
- artificial intelligence.
Data sovereignty policies can encourage local data-center development.
However, excessive localization requirements can increase costs and reduce efficiency.
A balanced policy must therefore protect important data without unnecessarily fragmenting the global Internet.
20. Data Centers and Economic Development
A data center can contribute to an economy through:
- construction;
- engineering;
- electricity infrastructure;
- telecommunications;
- employment;
- tax revenues;
- technology services;
- cloud availability;
- foreign investment.
But the economic benefits should not be overstated.
Highly automated data centers can operate with relatively small permanent workforces compared with traditional industries.
The greatest long-term benefit may therefore come indirectly.
For example:
Data center → Cloud availability → Digital businesses → AI adoption → Productivity → Economic growth
This broader ecosystem can be more important than the facility’s direct employment.
21. Data Centers and Artificial Intelligence
AI has fundamentally changed the data-center industry.
Traditional enterprise applications may use relatively modest computing resources.
Large AI models can require enormous amounts of:
- GPUs or other accelerators;
- memory;
- storage;
- networking;
- electricity;
- cooling.
AI therefore increases the importance of data-center scale.
The modern data center is increasingly becoming a combination of:
Power plant + computing factory + telecommunications hub + industrial cooling system.
22. The New Geography of AI
Historically, data centers often developed near:
- financial centers;
- Internet exchanges;
- major cities;
- large business markets.
AI is changing this model.
AI training facilities can be located farther from cities if they have:
- enormous power availability;
- affordable land;
- high-capacity fiber;
- suitable cooling;
- reliable infrastructure.
Recent European development patterns demonstrate this transition, with AI-oriented facilities moving farther from major metropolitan centers because power and land have become critical constraints.
This could produce a new geography of computing.
The most important location may increasingly be determined by:
electricity + land + fiber + cooling
rather than simply population density.
23. The Data-Center Supply Chain
A data center depends on a global industrial ecosystem.
Important components include:
Semiconductors
Processors, GPUs, networking chips and memory.
Servers
Systems that contain processors, memory, storage and networking.
Networking
Switches, routers, optical transceivers and fiber systems.
Power
Transformers, switchgear, UPS systems, batteries and generators.
Cooling
Chillers, pumps, heat exchangers and cooling systems.
Construction
Steel, concrete, electrical systems and specialized engineering.
Software
Virtualization, orchestration, monitoring and security.
Therefore, data centers connect many industries.
24. Data Centers and Submarine Cables
International data traffic depends heavily on submarine fiber-optic cables.
These cables connect continents.
A simplified international digital pathway is:
User → Local Network → Data Center → Fiber Network → Submarine Cable → International Network → Destination Data Center
Countries with excellent submarine-cable connectivity have a major advantage.
However, cables alone are insufficient.
A country also requires:
Cable landing stations + terrestrial fiber + Internet exchanges + data centers.
25. Internet Exchanges
Internet exchange points allow networks to exchange traffic directly.
This can reduce:
- latency;
- international transit costs;
- dependence on distant networks.
A strong Internet exchange ecosystem can therefore support local data-center development.
26. Why Local Data Centers Matter
Suppose a user in an African country accesses an application hosted thousands of kilometers away.
The traffic may travel internationally even though the user and application are serving the same broad regional market.
Local data centers can reduce this distance.
Benefits include:
- lower latency;
- improved resilience;
- reduced international bandwidth requirements;
- greater data sovereignty;
- better cloud availability;
- stronger digital ecosystems.
This is why data-center development should be considered part of national digital infrastructure.
27. The Data Desert and the Digital Divide
The digital divide is no longer simply about whether people have Internet access.
It increasingly has multiple layers.
First layer
Connectivity divide
Who has Internet access?
Second layer
Speed divide
Who has high-quality broadband?
Third layer
Computing divide
Where is computing infrastructure located?
Fourth layer
AI divide
Who has access to advanced AI computing?
Fifth layer
Innovation divide
Who can build new technologies using that infrastructure?
This suggests a new concept:
The global digital divide is becoming an infrastructure-and-compute divide.
28. Africa’s Strategic Opportunity
Africa’s data-center shortage should not only be viewed as a problem.
It is also a major investment opportunity.
Africa has:
- a young population;
- rapidly increasing digital adoption;
- expanding mobile connectivity;
- growing fintech;
- emerging AI markets;
- increasing cloud adoption;
- expanding digital government;
- renewable-energy potential.
The continent therefore has the potential to develop a much larger digital infrastructure industry.
29. South Africa as an African Data-Center Hub
South Africa has emerged as one of the most important data-center markets on the continent.
Its advantages include:
- relatively developed telecommunications infrastructure;
- major financial markets;
- submarine-cable connections;
- established cloud ecosystems;
- a large digital economy;
- technical skills;
- regional connectivity.
Johannesburg and Cape Town are particularly important.
South Africa can potentially serve as a gateway connecting African markets to global cloud and Internet infrastructure.
However, electricity reliability and infrastructure constraints remain important strategic considerations.
30. The Need for Distributed African Infrastructure
Africa should not depend on one country or one city.
A resilient continental architecture could involve multiple hubs.
For example:
Southern Africa
- South Africa
- regional neighboring markets
East Africa
- Kenya
- Tanzania
- Rwanda
- Uganda
West Africa
- Nigeria
- Ghana
- Côte d’Ivoire
- Senegal
North Africa
- Egypt
- Morocco
- other Mediterranean-connected markets
Central Africa
- strategically located regional facilities
The objective should be a network rather than a single dominant center.
31. Renewable Energy and Data Centers
Data centers are electricity-intensive facilities.
Renewable energy can help reduce carbon emissions.
Potential sources include:
- solar;
- wind;
- hydroelectricity;
- geothermal;
- nuclear power as a low-carbon source;
- battery storage.
Africa possesses substantial renewable-energy potential.
The challenge is converting resource potential into:
Reliable 24-hour electricity.
Solar and wind are variable.
Therefore, renewable data-center strategies require appropriate combinations of:
Generation + storage + grid + backup + demand management.
32. Water and Environmental Sustainability
Data-center growth creates environmental questions.
Major issues include:
- electricity consumption;
- carbon emissions;
- water use;
- land use;
- electronic waste;
- construction materials.
A sustainable data center must consider its entire lifecycle.
This includes:
Construction → Operation → Cooling → Electricity → Hardware replacement → Recycling → Decommissioning
33. The Circular Data Center
Future data centers should increasingly adopt circular-economy principles.
Hardware should be:
- repaired;
- reused;
- refurbished;
- recycled where practical.
Heat can potentially be recovered.
For example:
Data center → Waste heat → District heating / industrial use
This is particularly attractive in colder regions.
34. Reliability and Redundancy
A major data center cannot rely upon a single point of failure.
It therefore uses redundancy.
Examples include:
- multiple power feeds;
- backup generators;
- UPS systems;
- redundant cooling;
- multiple network paths;
- duplicate storage;
- backup facilities.
The objective is high availability.
A sophisticated data-center strategy therefore asks:
What happens if one component fails?
and designs the system so that the service continues.
35. Cybersecurity
Data centers are major cybersecurity targets because they contain valuable computing infrastructure and information.
Security must operate at several levels:
Physical security
Protecting buildings and equipment.
Network security
Protecting communications.
System security
Protecting servers and operating systems.
Application security
Protecting software.
Data security
Protecting information.
Identity security
Ensuring that only authorized users access systems.
The modern data center is therefore simultaneously a physical infrastructure system and a cybersecurity environment.
36. Artificial Intelligence for Data-Center Operations
AI can help operate data centers.
Applications include:
- predictive maintenance;
- anomaly detection;
- energy optimization;
- cooling optimization;
- workload scheduling;
- capacity planning;
- fault prediction.
The Uptime Institute’s 2025 global survey shows growing interest in AI-assisted data-center operations, although operators remain cautious about allowing AI to make highly consequential operational decisions autonomously.
This suggests that the future will probably involve human-supervised AI operations rather than completely autonomous facilities.
37. The Data Center as a National Strategic Asset
Data centers should increasingly be considered alongside:
- electricity grids;
- airports;
- ports;
- telecommunications networks;
- railways;
- financial infrastructure.
They are becoming strategic infrastructure.
A country without sufficient computing capacity may become increasingly dependent on foreign infrastructure.
That dependence can affect:
- economic competitiveness;
- government services;
- AI development;
- cybersecurity;
- digital sovereignty.
38. The Future Global Data-Center Map
The global map is likely to become more diversified.
Traditional powerhouses will remain important:
United States → China → Europe → Japan → Singapore
But emerging centers will increasingly matter:
India → Malaysia → Indonesia → Middle East → Latin America → Africa
The biggest transformation may be the rise of secondary cities and regions with abundant electricity.
39. From Metropolitan Data Centers to Energy-Driven Data Centers
The old model:
Customer proximity → data center
The emerging model:
Power availability + land + fiber + cooling → data center
The two models will coexist.
Low-latency applications will continue to require facilities close to users.
AI training and large-scale cloud computing can increasingly move toward locations with abundant infrastructure.
This creates a two-level architecture:
Urban edge computing
plus
Large remote AI/hyperscale computing
40. Closing the Global Data-Center Gap
The data-center gap cannot be solved simply by constructing buildings.
A successful national strategy requires an ecosystem.
Pillar 1: Electricity
Reliable, affordable and scalable power.
Pillar 2: Fiber
High-capacity domestic and international connectivity.
Pillar 3: Land
Suitable industrial land.
Pillar 4: Finance
Long-term infrastructure capital.
Pillar 5: Skills
Engineering and technology expertise.
Pillar 6: Regulation
Predictable investment rules.
Pillar 7: Cybersecurity
Strong protection of infrastructure and data.
Pillar 8: Cloud Ecosystem
Availability of major cloud and digital services.
Pillar 9: Local Demand
Enterprises and governments capable of consuming computing services.
Pillar 10: Sustainability
Responsible management of electricity, water and waste.
41. A Strategic Development Model for Data-Desert Countries
A developing country could approach data-center development through five stages.
Stage 1: Digital Foundation
Develop:
- national fiber;
- Internet exchanges;
- submarine-cable connections;
- reliable electricity.
Stage 2: Regional Data Centers
Develop smaller facilities serving domestic enterprises and government.
Stage 3: Cloud Ecosystem
Attract cloud providers and colocation operators.
Stage 4: Hyperscale Development
Develop large campuses when power and demand justify them.
Stage 5: AI Infrastructure
Develop specialized AI computing facilities.
This progression is more realistic than immediately attempting to construct enormous hyperscale campuses without supporting infrastructure.
42. Measuring a Country’s Data-Center Readiness
A useful national scorecard could measure:
| Indicator | Question |
|---|---|
| Electricity | Is reliable power available? |
| Grid | Can the grid support large facilities? |
| Fiber | Is high-capacity connectivity available? |
| Submarine cables | Is international connectivity strong? |
| Land | Is suitable land available? |
| Cooling | Are sustainable cooling options available? |
| Capital | Can large projects obtain financing? |
| Skills | Are qualified technicians available? |
| Regulation | Is policy predictable? |
| Security | Is infrastructure physically and digitally secure? |
| Demand | Is there sufficient local digital demand? |
| Sustainability | Can environmental impacts be controlled? |
A country that performs strongly across these categories has the foundations of a competitive data-center industry.
43. The Economics of Data Centers
The economics of a data center can be represented as:
Capital expenditure + electricity + cooling + networking + maintenance + land + financing
against:
colocation revenue + cloud revenue + computing revenue + storage revenue + connectivity revenue
Electricity is particularly important because computing facilities operate continuously.
This means that electricity pricing and availability can directly influence competitiveness.
44. Why Data Centers Follow Electricity
A data center can purchase additional servers relatively quickly.
But constructing electricity-generation and transmission infrastructure can take much longer.
Therefore:
Computing equipment can be mobile; electricity infrastructure is geographically constrained.
This explains why power availability is increasingly determining data-center location.
45. Data Centers and National Industrial Policy
Governments can treat data centers as anchors for wider technology ecosystems.
A data center can support:
- cloud companies;
- AI startups;
- software developers;
- financial technology;
- universities;
- government digital services;
- telecommunications;
- cybersecurity companies.
The strategic objective should therefore not simply be:
“Build a data center.”
It should be:
“Build a computing ecosystem.”
46. The Risk of Data-Center Concentration
Concentration provides economies of scale but also creates risks.
If too much computing infrastructure is concentrated in a few regions, the world becomes vulnerable to:
- grid failures;
- natural disasters;
- geopolitical tensions;
- cable failures;
- regulatory changes;
- cyber incidents;
- extreme weather.
Geographical diversification therefore improves resilience.
47. Data Centers and Geopolitics
Data centers are becoming part of technological competition.
Countries increasingly compete for:
- AI infrastructure;
- semiconductor supply;
- cloud computing;
- energy;
- talent;
- capital.
The ability to host computing infrastructure can influence a nation’s technological independence.
This is particularly important in AI.
A country may have excellent researchers but limited access to advanced computing.
Conversely, a country may possess large computing infrastructure but lack sufficient AI talent.
The strongest ecosystems combine:
Talent + Capital + Chips + Data + Energy + Computing.
48. The Future of Data Centers in Africa
Africa’s opportunity is substantial.
The continent could develop a network of:
- metropolitan data centers;
- regional cloud hubs;
- edge facilities;
- AI computing centers;
- Internet exchanges;
- renewable-energy-powered campuses.
The greatest opportunity may arise from combining digital infrastructure with energy development.
For example:
Solar/Wind/Hydro → Grid → Data Center → Cloud → AI → Digital Economy
This could create a powerful development cycle.
49. Policy Recommendations
Governments seeking to reduce their data-center gap should consider the following strategic priorities.
1. Strengthen electricity infrastructure
Data centers require reliable power.
2. Expand national fiber networks
Domestic connectivity is as important as international connectivity.
3. Improve submarine-cable diversity
Multiple international connections improve resilience.
4. Develop Internet exchanges
Local traffic should remain local where economically appropriate.
5. Create predictable investment frameworks
Investors need long-term certainty.
6. Develop technical skills
Data centers require specialized engineering talent.
7. Encourage renewable energy
This can reduce environmental impact and potentially improve long-term energy security.
8. Develop regional data-center clusters
Multiple hubs are more resilient than a single national facility.
9. Support cloud adoption
Local computing infrastructure becomes more valuable when enterprises use cloud services.
10. Build AI capacity
AI should become an important part of national computing strategies.
50. A Vision for a More Balanced Digital World
The objective should not be to make every country contain a massive hyperscale data center.
That would be economically inefficient.
Instead, the goal should be appropriate computing capacity for each region.
A balanced global architecture might look like:
Global Hyperscale Centers
↓
Regional Cloud Centers
↓
National Data Centers
↓
Edge Data Centers
↓
Businesses / Government / Universities / Consumers
This architecture combines scale with accessibility.
51. Conclusion
The global data-center industry represents the physical foundation of the digital economy.
Behind the apparent simplicity of “the cloud” exists a massive infrastructure composed of electricity networks, buildings, servers, processors, storage systems, cooling technologies, fiber-optic networks, submarine cables, software, cybersecurity systems and skilled professionals.
The distribution of this infrastructure is highly unequal.
The United States and China possess enormous concentrations of capacity, while Europe, Asia-Pacific and other regions contain major and rapidly expanding ecosystems. Meanwhile, Africa, South Asia, parts of Latin America and other developing regions face significant infrastructure gaps. The ITU’s analysis illustrates the scale of these regional gaps, including an estimated 6 GW gap for Africa and 9.4 GW for South Asia under its methodology.
This inequality produces the phenomenon described in this thesis as digital powerhouses and data deserts.
However, the map is changing.
Artificial intelligence is transforming data centers from relatively conventional server facilities into massive computing infrastructures whose requirements increasingly resemble those of industrial plants. Electricity, land, cooling and fiber connectivity are becoming decisive factors in determining where the next generation of facilities will be built.
The future therefore belongs not simply to countries with large populations or advanced software industries, but increasingly to countries capable of combining:
Reliable Electricity + Advanced Computing + Fiber Connectivity + Capital + Engineering Skills + Data + AI Talent + Sustainable Infrastructure.
The central strategic lesson is clear:
A nation’s digital economy is ultimately limited by the physical infrastructure available to power, connect, store and process its information.
Closing the world’s data-center gaps will therefore require much more than constructing server buildings. It requires coordinated investment in electricity, telecommunications, cloud computing, AI, education, cybersecurity, regulation and sustainable infrastructure.
The transition from today’s digital powerhouses and data deserts toward a more balanced global computing ecosystem represents one of the defining infrastructure challenges of the twenty-first century.
Selected Research Sources
- International Telecommunication Union — Connecting Humanity / Investment and infrastructure research — Provides regional analysis of data-center capacity gaps.
- CBRE — Global Data Center Trends 2025 — Provides market, capacity, vacancy and regional development analysis.
- Uptime Institute — Provides research on data-center operations, technology and infrastructure.
- KPMG — Provides analysis of the Asian data-center landscape and regional capacity growth.
Final Thesis Statement
Data centers are the factories of the information age. The countries and regions that can reliably generate, connect, cool, secure and operate computing capacity will possess a growing strategic advantage in cloud computing, artificial intelligence and the wider digital economy. The great infrastructure challenge ahead is therefore not merely connecting the world to the Internet, but ensuring that the world’s computing power is distributed sufficiently, sustainably and resiliently to support the next generation of human development.

Be First to Comment