
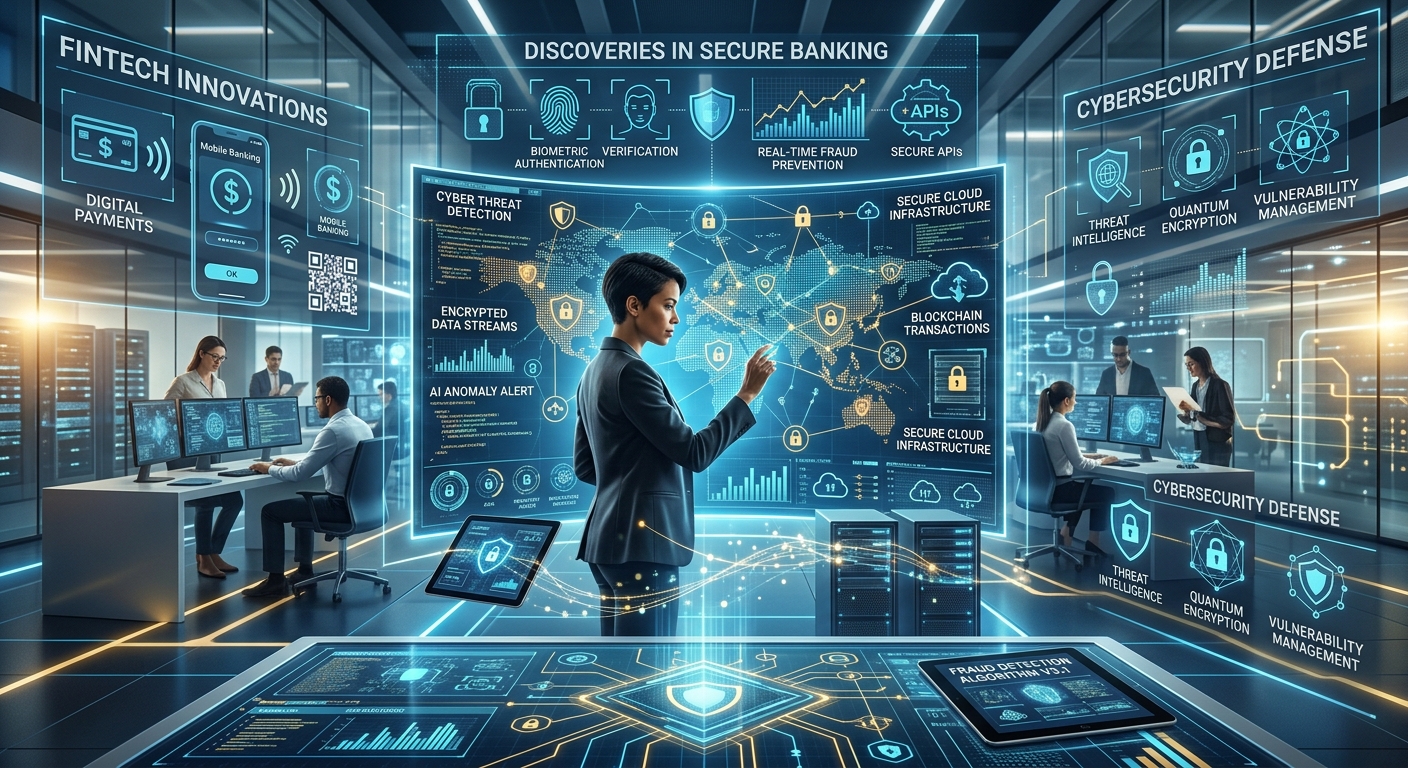
Patterns, Inventions, Discoveries and the Architecture of the Digital Financial Economy — 2026
Abstract
The modern financial system is no longer simply a collection of banks, branches, cash machines and payment cards. It has become a large interconnected digital ecosystem in which banks, fintech companies, telecommunications networks, cloud platforms, payment processors, governments, merchants, consumers, artificial-intelligence systems and regulatory institutions exchange information and value continuously.
This transformation has produced a new relationship:
Money → Data → Networks → Algorithms → Identity → Trust → Security → Financial Services
Cybersecurity is therefore no longer merely an IT department’s responsibility. It has become part of the fundamental architecture of financial stability.
Recent 2026 research from the IMF, BIS, FATF and Financial Stability Board highlights a particularly important development: artificial intelligence is increasing both the defensive capabilities and the potential scale and speed of cyber threats against financial systems. IMF
Chapter 1 — Understanding the Modern Financial Cyber Space
A useful way to understand today’s financial ecosystem is as a series of interconnected layers.
                 DIGITAL FINANCIAL ECOSYSTEM
                           │
          ┌────────────────┴────────────────┐
          │                                 │
       FINANCIAL                         DIGITAL
       SERVICES                         INFRASTRUCTURE
          │                                 │
    ┌─────┼─────┐                    ┌──────┼──────┐
    │     │     │                    │      │      │
  Banks FinTech Insurance          Cloud  Telecom Internet
    │     │     │                    │      │      │
    └─────┼─────┘                    └──────┼──────┘
          │                                 │
          └──────────────┬──────────────────┘
                         │
                    DATA + APIs
                         │
                 Identity Systems
                         │
                   AI / Analytics
                         │
                    Cybersecurity
                         │
                      TRUST
                         │
                      MONEY
The critical discovery is that financial value increasingly travels through information systems.
A payment may appear simple to the customer:
Person A → sends money → Person B
Behind that transaction can be:
Device → authentication → application → API → bank → payment switch → fraud engine → clearing system → settlement system → recipient bank → notification.
Cybersecurity must protect every important transition.
Chapter 2 — From Traditional Banking to Digital Banking
Traditional banking historically relied heavily on:
- physical branches
- paper records
- human verification
- cash
- cheques
- physical signatures
- proprietary bank systems.
Modern banking increasingly uses:
- mobile applications
- internet banking
- APIs
- biometric authentication
- digital identity
- cloud computing
- instant payments
- artificial intelligence
- machine learning
- distributed databases
- automated compliance
- electronic settlement.
This represents a fundamental technological change.
Old model
Customer → Branch → Bank employee → Core banking system
Modern model
Customer → Smartphone → Internet → API → Authentication → Automated systems → Core banking → Payment network
The modern model is dramatically faster, but its interconnectedness creates additional points where security, availability and operational resilience matter.
Chapter 3 — The Seven Major Patterns of Modern Financial Cybersecurity
Pattern 1: Identity becomes the new perimeter
In older networks, security was often described in terms of protecting a physical or corporate network.
Today, the more important question is:
Who is requesting this transaction, from which device, under what circumstances?
Modern identity architecture can combine:
- passwords
- passkeys
- multi-factor authentication
- biometrics
- device identity
- behavioural signals
- transaction history
- location-related signals
- risk scoring.
The security system attempts to determine whether the person, device and transaction are consistent with legitimate behaviour.
Chapter 4 — Pattern 2: Zero-Trust Architecture
A major modern cybersecurity principle is zero trust.
The basic idea is not:
“This person is inside the network, therefore they are trusted.”
Instead:
“Every access request must be evaluated according to identity, authorization, device, context and risk.”
Conceptually:\[ Trust = f(I,D,C,A,R) \]
where:
- \(I\) = identity
- \(D\) = device
- \(C\) = context
- \(A\) = authorization
- \(R\) = risk.
This is particularly important for banks because employees, customers, APIs, cloud services and automated systems may all interact with sensitive financial infrastructure.
Chapter 5 — Pattern 3: Artificial Intelligence and Cybersecurity
AI is becoming a two-sided technology.
Defensive side
AI can help financial institutions:
- identify unusual transactions
- detect suspicious behaviour
- classify security events
- prioritize alerts
- discover vulnerabilities
- analyse large quantities of logs
- identify patterns invisible to manual inspection.
Offensive side
The same technological advances can potentially help attackers automate aspects of:
- vulnerability discovery
- social engineering
- malicious-code development
- reconnaissance
- fraud campaigns.
The IMF’s 2026 analysis emphasizes that AI may amplify existing cyber risks through speed, scale and shared infrastructure, rather than necessarily creating entirely new categories of attacks. IMF
The BIS similarly reports that frontier AI can increase both cyberattack capabilities and cyber-defence capabilities, with the balance depending on access to advanced models, computing resources and economic incentives. Bank for International Settlements
Chapter 6 — Pattern 4: Digital Fraud Becomes a Cybersecurity Problem
Cybersecurity and financial fraud can no longer be treated as completely separate disciplines.
Consider:
Cyber event
     ↓
Compromised information
     ↓
Manipulated identity / transaction
     ↓
Fraud
     ↓
Financial loss
     ↓
Potential money laundering
The FATF reported in 2026 that cyber-enabled fraud has become a major source of illicit proceeds and examined how digitalisation connects fraud with money-laundering risks. FATF
The IMF likewise identifies a close relationship between cyber incidents and digital fraud because weaknesses in digital systems can facilitate both institutional attacks and fraud against users. IMF
Chapter 7 — Pattern 5: Open Banking
Open banking represents another major transformation.
Instead of a bank operating as an isolated technological island, authorized third parties can interact with financial information or payment functionality through controlled interfaces.
The basic architecture is:
Customer
   │
   ▼
FinTech Application
   │
   ▼
Secure API
   │
   ▼
Bank
   │
   ├── Account Information
   │
   └── Payment Initiation
APIs therefore become a major technological bridge between traditional financial institutions and fintech.
But APIs also become security-critical infrastructure.
The challenge becomes:
How do you create openness without sacrificing security, privacy and consumer protection?
Chapter 8 — Pattern 6: Instant Payments
Traditional payment systems could involve significant processing delays.
Modern payment systems increasingly seek:
24/7 + near-real-time + mobile + interoperable
architecture.
South Africa provides an interesting example. The IMF’s 2026 country assessment notes the continued development of instant payments through PayShap, mobile-money services, tap-on-phone solutions and emerging open-banking initiatives. IMF eLibrary
The architecture can be simplified as:
Person A
   │
Mobile Device
   │
Payment App
   │
Payment Infrastructure
   │
Clearing / Switching
   │
Recipient Bank
   │
Person B
The major technological discovery here is that payment speed changes the security problem.
If money moves almost immediately, fraud detection and transaction controls must increasingly operate almost immediately too.
Chapter 9 — Pattern 7: Cloud Banking
Modern financial institutions increasingly depend upon:
- cloud infrastructure
- software-as-a-service
- distributed computing
- managed databases
- containerized applications
- microservices
- APIs.
This creates scalability.
For example:
                 CLOUD
                   │
       ┌───────────┼───────────┐
       │           │           │
   Compute      Database     Storage
       │           │           │
       └───────────┼───────────┘
                   │
                 APIs
                   │
        Banking Applications
But concentration matters.
If multiple financial institutions depend on common technology providers, a problem affecting shared infrastructure can potentially affect many institutions simultaneously.
This is one reason the IMF emphasizes limiting the “blast radius” of cyber incidents and strengthening recovery capabilities. IMF
Chapter 10 — The New Banking Technology Stack
A modern digital bank can be represented as:
                    CUSTOMER
                       │
             ┌─────────┴─────────┐
             │                   │
        Mobile App           Web App
             │                   │
             └─────────┬─────────┘
                       │
                     APIs
                       │
              Identity / IAM
                       │
              Security Layer
                       │
             ┌─────────┴─────────┐
             │                   │
        AI/Fraud Engine       Analytics
             │                   │
             └─────────┬─────────┘
                       │
                 Core Banking
                       │
       ┌───────────────┼───────────────┐
       │               │               │
   Payments          Loans          Deposits
       │               │               │
       └───────────────┼───────────────┘
                       │
             External Financial
                Infrastructure
Cybersecurity surrounds practically every layer.
Chapter 11 — The Invention of the Digital Financial Identity
One of the most significant developments in fintech is the movement from:
physical identity → digital identity
A digital financial identity can connect:
- customer information
- authentication credentials
- devices
- accounts
- transactions
- permissions
- risk signals.
This produces a new concept:
Digital identity = gateway to financial participation.
Consequently, protecting identity is often as important as protecting the account itself.
Chapter 12 — Biometrics
Financial systems increasingly use biometric technologies such as:
- fingerprint recognition
- facial recognition
- voice-related authentication
- behavioural characteristics.
The advantage is convenience.
The challenge is that biometric information is fundamentally different from a password.
A password can be changed.
A person’s biological characteristics cannot simply be replaced.
Therefore biometric systems require strong protection of the underlying templates and authentication infrastructure.
Chapter 13 — Cryptography: The Mathematical Foundation
Modern banking cybersecurity ultimately depends heavily on mathematics.
Cryptography transforms information into a form that unauthorized parties cannot readily interpret.
A simplified encryption model is:\[ C = E_K(P) \]
where:
- \(P\) = plaintext
- \(K\) = cryptographic key
- \(E\) = encryption algorithm
- \(C\) = ciphertext.
Decryption is:\[ P = D_K(C) \]
Cryptography supports:
- confidentiality
- authentication
- integrity
- digital signatures
- secure communications
- transaction authorization.
Chapter 14 — Public-Key Cryptography
Public-key cryptography introduced a revolutionary concept:
Public Key  → can be distributed
Private Key → must remain protected
This supports secure communications and digital signatures.
A simplified digital-signature model is:
Message
   ↓
Hash
   ↓
Digital Signature
   ↓
Verification
   ↓
Authentic / Not Authentic
This mathematical architecture is fundamental to modern digital trust.
Chapter 15 — Blockchain and Distributed Ledger Technology
Blockchain introduced another important financial technology architecture.
Traditional banking databases generally operate under controlled institutional governance.
Distributed ledger systems instead distribute transaction records across participating nodes according to a consensus mechanism.
Conceptually:
Transaction
     ↓
Validation
     ↓
Consensus
     ↓
Ledger Update
     ↓
Cryptographically Linked Record
Applications investigated across finance include:
- tokenisation
- settlement
- digital assets
- programmable financial instruments
- cross-border transactions.
Blockchain, however, does not automatically make a financial system secure. Security depends on the entire architecture surrounding the ledger.
Chapter 16 — Tokenisation
Tokenisation represents another major financial innovation.
The underlying idea is that an asset or financial claim can be represented digitally as a token within a technological infrastructure.
Conceptually:\[ Physical/Financial\ Asset \rightarrow Digital\ Representation \rightarrow Programmable\ Infrastructure \]
Potential applications include representations of:
- securities
- deposits
- financial claims
- other assets.
The important concept is that ownership, transfer and settlement can increasingly become software-mediated processes.
Chapter 17 — Central Bank Digital Currency
Another major area of financial experimentation is the central bank digital currency, or CBDC.
Its architecture can be represented conceptually as:
Central Bank
     │
Digital Monetary Infrastructure
     │
┌────┴─────┐
│          │
Banks    Payment
         Providers
│          │
└────┬─────┘
     │
Citizens / Businesses
The technological questions include:
- identity
- privacy
- offline functionality
- transaction limits
- interoperability
- cybersecurity
- monetary-system architecture.
CBDC design is therefore not simply a question of creating “digital money”; it is an institutional and technological architecture problem.
Chapter 18 — FinTech as a New Financial Architecture
FinTech is broader than mobile banking.
It includes:
Payments
Digital wallets, instant payments and payment gateways.
Lending
Digital credit assessment and automated underwriting.
Investment
Digital investment platforms and algorithmic analysis.
Insurance
Digital insurance platforms and automated claims processes.
Accounting
Cloud accounting and automated reconciliation.
Wealth management
Digital portfolio and financial-management tools.
RegTech
Technology supporting regulatory compliance.
SupTech
Technology used by financial supervisors.
Embedded finance
Financial services integrated directly into non-financial applications.
Chapter 19 — Embedded Finance
This is one of the most important patterns in the modern fintech economy.
Instead of:
Customer → Bank → Financial service
the architecture increasingly becomes:
Customer → Digital platform → Embedded financial service
For example, a commercial platform might incorporate:
- payments
- financing
- insurance
- wallets
- financial management.
The distinction between a “banking application” and a “normal digital application” therefore becomes increasingly blurred.
Chapter 20 — RegTech and SupTech
Technology is not only changing financial institutions.
It is changing regulators too.
RegTech
Financial institutions use technology to automate:
- compliance
- reporting
- transaction monitoring
- identity verification
- risk analysis.
SupTech
Supervisory authorities can use technology for:
- data analysis
- risk monitoring
- early-warning systems
- regulatory reporting
- systemic-risk analysis.
This creates a new architecture:
Financial Institution
        │
        ▼
   Financial Data
        │
        ▼
RegTech / Compliance
        │
        ▼
     Regulator
        │
        ▼
     SupTech
        │
        ▼
Systemic Risk Monitoring
Chapter 21 — Cyber Resilience Versus Cybersecurity
These terms are related but different.
Cybersecurity
Attempts to prevent, detect and protect against cyber incidents.
Cyber resilience
Asks a larger question:
Can the financial institution continue operating, recover and restore critical services after an incident?
This distinction is increasingly important.
The Basel Committee reported in 2026 that ICT risk management is a key component of operational risk management and operational resilience in banking. Bank for International Settlements
Therefore:\[ Security \neq Resilience \]
A mature financial institution needs both.
Chapter 22 — The Modern Cybersecurity Control Loop
A sophisticated financial cybersecurity architecture can be understood as a continuous loop:
IDENTIFY
   ↓
PROTECT
   ↓
DETECT
   ↓
RESPOND
   ↓
RECOVER
   ↓
LEARN
   ↓
IMPROVE
   └──────────────→ IDENTIFY
This is fundamentally different from the older philosophy of:
Build a firewall and assume the problem is solved.
Modern cybersecurity assumes that systems must continuously monitor, adapt and recover.
Chapter 23 — The Data Economy
Modern financial institutions generate enormous quantities of data.
Examples include:
- transactions
- account activity
- payment metadata
- customer interactions
- application information
- fraud signals
- credit information
- device information.
This creates a strategic equation:\[ Data + Computing + Algorithms = Financial Intelligence \]
But:\[ More\ Data + More\ Connectivity = Larger\ Attack\ Surface \]
This is one of the fundamental paradoxes of digital finance.
Chapter 24 — The Financial Attack Surface
A modern bank may have:
Mobile Applications
       │
Web Applications
       │
APIs
       │
Cloud
       │
Employees
       │
Customers
       │
Third-party Vendors
       │
Payment Networks
       │
ATMs / Devices
       │
Telecommunications
       │
Data Centres
Every connection potentially introduces technological dependency.
Therefore modern cybersecurity increasingly involves ecosystem security, not merely enterprise security.
Chapter 25 — Third-Party and Supply-Chain Risk
A financial institution can have excellent internal cybersecurity while depending on external organizations for:
- cloud computing
- telecommunications
- software
- cybersecurity services
- payment processing
- data services.
This creates the principle:
Your security is partly dependent on the security of your ecosystem.
The IMF’s 2026 work specifically highlights shared digital infrastructure and common service providers as potential channels through which cyber risks can become systemic. IMF
Chapter 26 — South Africa’s Emerging Financial Architecture
South Africa provides an important example of a rapidly evolving financial ecosystem.
Current developments include:
- instant payments
- PayShap
- mobile financial services
- tap-on-phone payments
- fintech payment services
- open-banking development
- open-finance policy work.
The IMF reports that South Africa’s authorities have been developing an open-banking framework, with payment initiation receiving priority and account-information services considered for a later stage. IMF eLibrary
South Africa has also implemented a financial-sector cybersecurity and cyber-resilience joint standard, effective from June 2025, covering governance, cybersecurity, resilience and material cyber-incident notification. IMF eLibrary
This illustrates the transition from:
traditional banking regulation
toward:
technology + data + cybersecurity + financial regulation.
Chapter 27 — The Emerging Cyber-Financial System
The next generation of finance can be represented as:
                   HUMAN
                     │
                     ▼
                DIGITAL ID
                     │
                     ▼
               SMART DEVICE
                     │
                     ▼
                   API
                     │
          ┌──────────┼──────────┐
          │          │          │
         AI        BANK       FINTECH
          │          │          │
          └──────────┼──────────┘
                     │
              PAYMENT SYSTEM
                     │
              SETTLEMENT SYSTEM
                     │
              DIGITAL MONEY
                     │
              GLOBAL ECONOMY
Cybersecurity operates across the entire structure.
Chapter 28 — The Most Important Modern Discovery: Trust Is Becoming Programmable
Perhaps the deepest conceptual change is that many activities previously dependent upon human institutions are increasingly mediated by software.
Historically:
Trust → human institutions
Modern finance:
Trust → institutions + cryptography + algorithms + identity + regulation + cybersecurity
This does not eliminate human institutions.
Instead, it creates a hybrid trust architecture.
Chapter 29 — The Cybersecurity–FinTech Equation
The modern financial system can therefore be described conceptually as:\[ Financial\ Innovation = Data + Connectivity + Computing + Algorithms + Identity + Regulation \]
while:\[ Financial\ Security = Cryptography + Identity + Monitoring + Governance + Resilience \]
And the long-term system becomes:\[ Digital\ Finance = Innovation + Trust + Security + Resilience \]
If one component becomes weak, the whole ecosystem can become less reliable.
Chapter 30 — The Future: 2026–2040
Several technological directions are likely to remain important:
1. AI-native banking
AI becomes integrated into customer service, risk management, fraud detection and financial operations.
2. Real-time finance
Payments and financial decisions increasingly operate continuously.
3. Open finance
Customers increasingly interact with multiple financial providers through interoperable interfaces.
4. Programmable finance
Software increasingly controls financial workflows.
5. Digital identity
Identity becomes an infrastructure layer across financial services.
6. Tokenised assets
More financial instruments may acquire digital representations.
7. Quantum-resistant cryptography
Financial institutions will need to consider cryptographic migration as quantum computing develops.
8. Autonomous security operations
AI-assisted systems increasingly monitor and respond to cyber events.
9. Cyber-resilient infrastructure
Banks will increasingly design systems around continuity and recovery, not merely prevention.
10. Greater regulatory technology
Regulators and financial institutions will increasingly analyse enormous quantities of financial and operational data.
Chapter 31 — The Central Challenge
The modern financial system faces a fundamental three-way relationship:
             INNOVATION
                /\
               /  \
              /    \
             /      \
         SECURITY — ACCESS
If technology becomes highly secure but inaccessible, financial inclusion can suffer.
If technology becomes highly accessible but poorly protected, fraud and cyber risk can increase.
If technology becomes highly innovative without sufficient resilience, systemic dependencies can become more significant.
The objective of modern financial architecture is therefore not simply more technology.
It is:
Trusted technology that can operate at scale, remain secure, protect users, support innovation and recover from disruption.
Conclusion
The modern cybersecurity, banking and fintech space represents one of the largest technological transformations in economic history.
The bank of the past was primarily a physical institution holding money and records.
The modern bank is increasingly a software-intensive, data-driven, networked institution operating within a broader digital ecosystem.
The fintech revolution extends that transformation beyond banks into payments, lending, insurance, investment, accounting, identity and commerce.
The cybersecurity revolution accompanies it because the more financial activity becomes digital, interconnected and automated, the more important identity, cryptography, APIs, AI, data governance, operational resilience and ecosystem security become.
The most significant development now emerging is the convergence of:
AI + cybersecurity + banking + fintech + digital identity + instant payments + cloud computing + regulation.
The IMF, BIS and FSB’s 2026 analyses all point toward the same broad structural issue: the speed and interconnectedness of digital financial systems can amplify both innovation and risk, making resilience and coordinated governance increasingly important. IMF
In simple terms:
The financial institution of the future will not merely protect money. It will protect identities, data, algorithms, digital infrastructure, transactions and trust itself.
Core architecture
                 THE MODERN FINANCIAL CIVILISATION

                         HUMAN USERS
                              │
                              ▼
                       DIGITAL IDENTITY
                              │
                              ▼
                         DEVICES/APPS
                              │
                              ▼
                            APIs
                              │
                ┌─────────────┼─────────────┐
                │             │             │
               BANK         FINTECH         AI
                │             │             │
                └─────────────┼─────────────┘
                              │
                       PAYMENT NETWORKS
                              │
                       CLEARING/SETTLEMENT
                              │
                       DIGITAL FINANCIAL
                         INFRASTRUCTURE
                              │
                ┌─────────────┼─────────────┐
                │             │             │
             CLOUD        TELECOM       DATA CENTRES
                │             │             │
                └─────────────┼─────────────┘
                              │
                       CYBERSECURITY
                              │
                        CYBER RESILIENCE
                              │
                           TRUST
                              │
                         ECONOMY
This architecture provides a useful foundation for studying modern banking, fintech, cybersecurity, digital money, AI finance and the future financial economy as one integrated technological system.

Be First to Comment